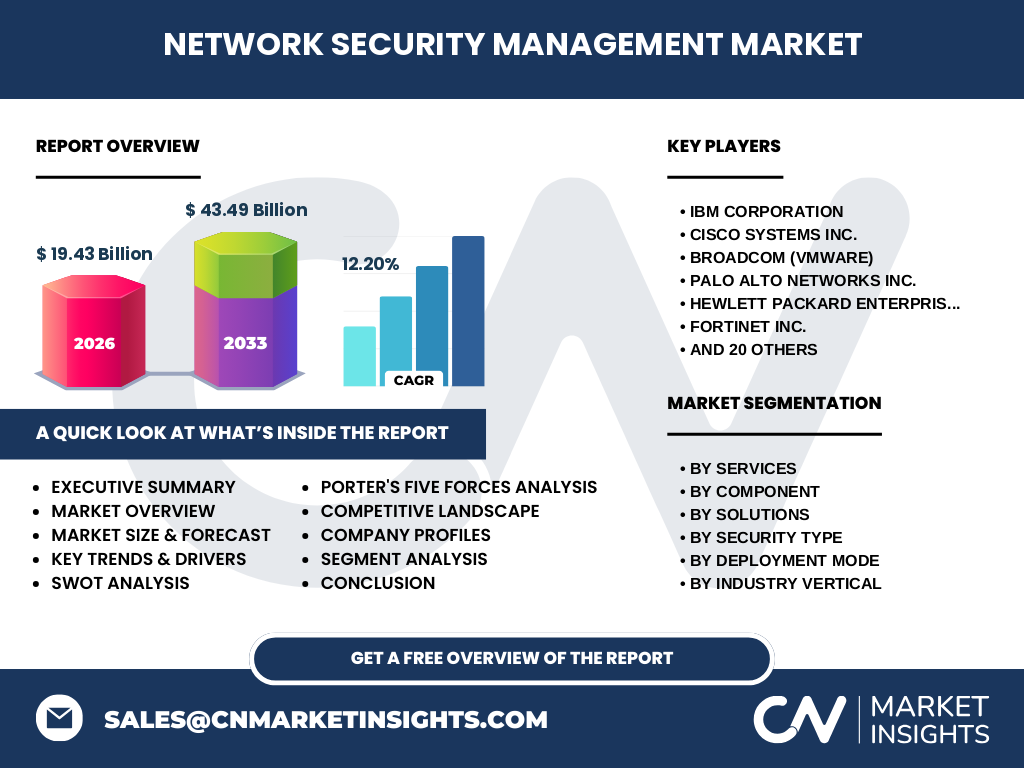
What is the scope and market size of the Network Security Management Market?
Our analysis indicates that the Network Security Management Market reached $19.43 Billion in 2026, driven by the critical necessity to secure distributed enterprise infrastructures against advanced persistent threats while maintaining compliance with frameworks like GDPR and HIPAA.
Structural Growth Drivers and Market Restraints
The market is propelled by a 12.20% CAGR through 2033, though stringent data localization laws and a severe shortage of certified cybersecurity professionals act as notable operational bottlenecks for scaling organizations.
Emerging Trends in Network Security Management
The shift toward Zero Trust Architecture and AI-driven automated threat hunting is redefining industry standards, favoring innovators capable of unifying disparate security telemetry across hybrid cloud ecosystems.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic drastically accelerated remote work adoption, forcing enterprises to rapidly expand perimeter defenses, which permanently restructured baseline IT security budgets toward cloud-native visibility solutions.
Competitive Benchmarking and Industry Concentration
Industry giants like Cisco Systems Inc., Palo Alto Networks Inc., and Fortinet Inc. dominate through comprehensive ecosystems, while pure-play vendors carve out profitable niches in specific detection vectors.
Executive Summary of the Network Security Management Industry
Projected to hit $43.49 Billion by 2033, the Network Security Management Market represents a mission-critical investment sector demanding strategic alignment with advanced automation and comprehensive threat intelligence capabilities.
Long-Term Market Forecast from 2027 to 2033
Driven by robust enterprise digital transformation initiatives, the market will expand steadily at a 12.20% CAGR from its 2026 valuation to achieve the projected $43.49 Billion by 2033 milestone.
Segmentation Analysis Across Solutions and Services
The market breaks down into Solutions (Firewall, IDS/IPS, VPN, SIEM, NAC) and Services (Consulting, Integration, Managed Security, Support, Training), with Managed Security Services experiencing the highest enterprise adoption rates.
Geographic Distribution and Regional Performance
North America retains the largest revenue share due to early adoption and strict regulatory mandates, while the Asia-Pacific region demonstrates the fastest growth trajectory driven by rapid cloud migration.
In-Depth Regional Review of High-Growth Zones
European markets prioritize stringent data privacy compliance under GDPR, whereas North American enterprises aggressively invest in advanced SIEM and endpoint detection technologies to combat sophisticated nation-state actors.
Strategic Positioning of Leading Market Companies
Market leaders such as IBM Corporation and CrowdStrike leverage integrated AI and threat intelligence platforms, while companies like Zscaler Inc. and Cloudflare Inc. dominate secure web gateway and edge security domains.
Porter's Five Forces Analysis of Competitive Pressure
High threat of substitution from proprietary cloud provider tools is balanced by intense rivalry among established security vendors and significant customer switching costs anchored in complex enterprise integrations.
SWOT Analysis of the Network Security Management Landscape
Key strengths include advanced automated threat remediation, while weaknesses involve high implementation costs; opportunities lie in SME cloud adoption, against threats from sophisticated quantum-enabled cyberattacks.
Value Chain Analysis from Development to End-Users
The value chain flows from foundational threat intelligence research and software development to system integration partners, ultimately delivering unified security visibility to BFSI, healthcare, and government end-users.
High-Potential Investment Insights and Strategic Areas
Investors should target niche innovators specializing in automated incident response and cloud security posture management, as these segments capture the highest enterprise willingness-to-pay.
Conclusion and Strategic Takeaways for Industry Stakeholders
Capturing growth in this $43.49 Billion market by 2033 requires vendors to seamlessly integrate AI-driven automation with multi-cloud visibility to address evolving enterprise threat surfaces effectively.
Proprietary Research Methodology and Data Triangulation
Baseline estimates are triangulated by combining primary stakeholder interviews with C-level CISOs, secondary macroeconomic indicators, and trade registry data to ensure high-fidelity market sizing and forecasting.
Scope of the Report and Coverage Parameters
This report covers global deployment models, organization sizes, and industry verticals from 2026 through 2033, excluding physical hardware manufacturing to focus strictly on software solutions and managed services.
Recent Industry Developments and Strategic Moves
Recent strategic acquisitions, such as Broadcom (VMware) integration milestones and major product launches by SentinelOne and CyberArk, highlight an industry-wide race toward consolidated platform ecosystems.